
Don’t Miss Out on FREE Government Money (Up to £121k each)

Every Sunday, I send you something to THINK about, a question to ASK yourself, something to TRY and invite you to SHARE.
Want to advertise in this Newsletter?
Book HERE
THINK
“I don’t care how much money you have, free stuff is always a good thing.”
Queen Latifah
There’s a limited-time opportunity for everyone aged roughly 40 to 73. You have until 5 April 2025 to buy back missing National Insurance contribution years from 2006 to 2016.
What this means in real terms…
With the State Pension, you can turn an £824 ‘investment’ into an income worth £302.64 /year.
- If you live for 20 years at the State Pension age (average), you’ll profit roughly £5,229 for each missing year you add. That’s a 535% Return on Investment.
- If you’re less optimistic and live for at least 3 years into retirement, you’re still in profit.
If you read last week’s Newsletter, you’ll understand that this is the equivalent of an investment pot worth £7,566 (£302.64 x 25).
You can buy multiple missing years (up to 16), meaning some people will be on course to receive £50,000-£100,000 from the Government.
If you’re below 40, it’s still worth reviewing the guide to understand the process. You can help a family member over 40. You may find a partial year worth topping up for yourself too.
Martin Lewis created a complete guide on voluntary National Insurance contributions HERE, and it’s worth checking out.
I’ve tried my best to condense the information and provide the key takeaways for you in this week’s Newsletter.
Boost Your State Pension
The new State Pension started on 6 April 2016.
The full State Pension is worth £203.85 /week at the time of writing.
- You need roughly 35 qualifying years of paying National Insurance (NI) to qualify for the full amount.
- Many people miss NI years due to living abroad, low income, career breaks, etc.
- You can ‘Buy’ back missing years (even weeks) to boost your pension to the full allocation.
When the new State Pension was brought in (2016), they offered ‘Transitional Arrangements’, meaning people could plug any gaps in their NI contributions back to 2006.
This opportunity was originally due to end on 5 April 2023. Due to the demand, the date was extended to 31 July 2023 and then again to 5 April 2025.
You have 14 months to claim the additional years before the ‘Transitional Arrangement’ date expires.
Big Profit Potential
A lady named Martine shared her win on MoneySavingExpert.com:
“I checked my NI contributions and found I had eight years missing! I’ve now paid six years and will pay the next two years when possible. This has made a difference of about £49 a week which is considerable! I’d never have known without the podcast! Thank you.”
Martine paid no more than £5,000 (it may’ve been far less) to increase her state pension by £2,550 a year. If she lives for the typical 20 years after the State Pension age, that’s a total uplift of roughly £51,000… and it’s inflation-proofed.
1. Check if you’re missing NI years (since 2006)
Go to Gov.UK and look up your NI record HERE.
You’ll see your record on the left-hand side. It will either say ‘Full year’ or ‘Year is not full’. The ‘View details’ link will give you more information on how many weeks are missing.
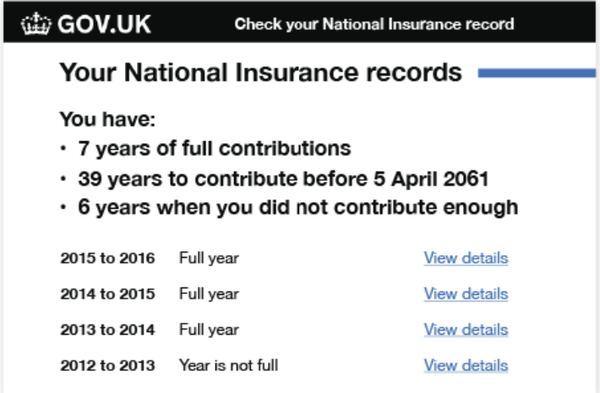
If you have any years missing since 2006, it might be worth plugging the gap to receive a higher state pension IF you’re not eligible for the full amount.
If you’re due the full State Pension of £203.85 /week, DON’T buy missing years. You can’t earn more.
2. Get a State Pension Forecast
Complete the Government’s ‘State Pension Forecast Calculator’ HERE for free.
It will provide you with two important details:
- How much State Pension you could get (based on your current NI record)
- When you will receive it.
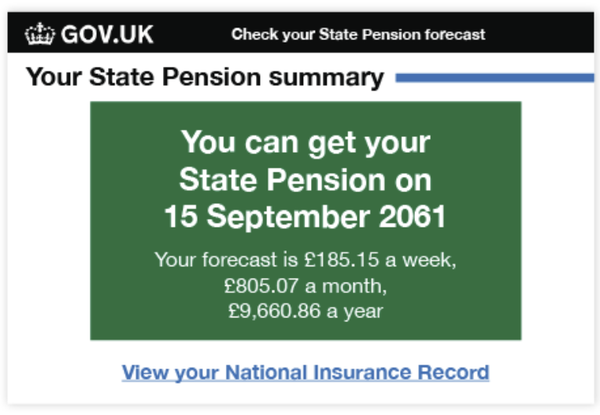
If you’re receiving or due to receive the full amount (£203.85 /week at the time of writing), you don’t need to do anything else.
Buying missing years will not do anything to your State Pension income outside of lining the Government’s pockets.
3. Do You Qualify for NI Credits
Before you buy any missing NI years, check if you’re due free ‘National Insurance Credits’.
AUTOMATIC – You can plug NI gaps outside of work. MoneySavingExpert.com has created a quick checklist to determine eligibility for automatic NI credits HERE.
- Eg. Low income, maternity allowance, careers allowance, Universal Credit or Jobseekers Allowance, illness, etc.
MANUAL – Some credits need to be claimed manually.
- Eg. Caring for a child in the family, Statutory sick pay, Unemployed looking for work, caring for a sick/disabled person, on Jury service, spouse of a member of the armed forces, etc.
Multiple scenarios make someone eligible. Find them all HERE.
If you qualify, use this free Pension Credit Calculator to see what you’re entitled to receive.
4. Should You Top Up Your State Pension?
If you’re missing NI years between 2006 and 2016 and don’t qualify for NI Credits (free contributions), you need to decide if it’s worth topping up before the current deadline of 5 April 2025.
Your age will largely determine this.
You’re at or near State Pension age
If your State Pension is, or is forecast to be, less than £203.85 /week at the time of writing, and you won’t be able to plug the gaps by any other means, topping up could be a no-brainer.
Aged above 40
The younger you are, the more time you have to earn enough qualifying years before you reach the State Pension age.
This is a personal decision. You need roughly 35 qualifying years (sometimes up to 44) of paying National Insurance (NI) to qualify for the entire State Pension.
Are you on track?
If so, it might not be worth it.
If not, weigh the cost of contributing versus the increased income you’d receive. (See #5 👇)
Aged below 40
It’s likely not worth the investment unless you’re sure you won’t make up for it due to something like living overseas.
5. What Topping Up is Worth
Unless you’re self-employed or living and working abroad, you must buy Class 3 NI contributions. Read Martin Lewis’s complete guide HERE.
The rate you pay depends on which year you’re buying. It ranges from £795.60 to £907.40 for the FULL year. (Average £824)
See below:
- 2006/07 to 2019/20 (inclusive) costs £824.20 (£15.85/week)
- 2020/21 costs £795.60 (£15.30/week)
- 2021/22 costs £800.80 (£15.40/week)
- 2022/23 costs £824.20 (£15.85/week)
- 2023/24 will cost £907.40 (£17.45/week)
- 2024/25 costs are yet to be confirmed
The maths is simple.
One full NI year costs approximately £824 and provides up to £302.64 /year to your State Pension.
You’re in profit if you live more than 3 YEARS after getting your pension (or 3 years after you top up if you already get it).
- If you live for 10 years at the State Pension age, you’ll profit roughly £2,202 for each missing year you add.
- If you live for 20 years at the State Pension age (average life expectancy), you’ll profit roughly £5,229 for each missing year you add.
- If you live for 30 years at the State Pension age, you’ll profit roughly £8,255 for each missing year you add.
Pay Weeks For a Year
You might not have to pay for the FULL 52 weeks to top up a year.
When you click on the ‘View details’ on your NI Record, you’ll see the size of your shortfall and how much it’ll cost to fill.
You can fill a year with weeks in some cases.
- Another reader from MoneySavingExpert.com, Caroline, found she was one week short of an entire year. She paid a week’s contribution (£15.40) and qualified for an additional £127.92 a year on her State Pension.
- She’ll receive £2,558.40 for 20 years of pension payments based on a £15.40 ‘investment’. That’s a 1,558% Return on Investment!
6. BEFORE PAYING – Call The Government’s Pension Helpline
I’ve tried summarising the key takeaways of the Government’s Transitional Arrangement.
Everyone’s circumstances are different, and there are multiple complexities, so I recommend the following:
- Read Martin’s complete guide HERE.
- Call the ‘Future Pension Centre’ (if you’re not receiving the State Pension) or the ‘Pension Service’ (if you’re receiving the State Pension) to get personalised information on your situation.
Both services provide specific information about your current NI record and whether buying missing years will increase your (eventual) state pension.
It’s possible to pay to plug a gap and see no gain, which is why this step is so important.
If you’re not at state pension age…
Contact the Future Pension Centre – 0800 731 0175.
It’s free to call but you might be waiting a while, as lines are very busy. The lines are open between 8am and 6pm, Monday to Friday.
If you’re already at state pension age…
If you’ve deferred your state pension or are already claiming it, contact the Pension Service at 0800 731 0469.
It’s also free to call; phone lines are open between 8am and 6pm, Monday to Friday.
7. How to Pay for Voluntary NI Contributions
If the Future Pension Centre or the Pension Service has confirmed that buying additional NI years will result in extra income and you’ve decided to top up, here’s how to do it:
- Decide how many NI years to buy – You don’t need to buy all the NI years in one go. You need to buy any missing years between 2006 and 2017 before 5 April 2025.
- Contact HMRC for an 18-digit reference number – Find the precise cost of the years you want to buy and get the reference you need. You’ll need to contact HM Revenue & Customs (HMRC). They can give you the number over the phone, or it takes 15 working days by post.
- Pay HMRC – Once you have the 18-digit reference number, send money through your bank to this HMRC bank account. Or pay by cheque, though HMRC says this takes longer to process.
- Wait for the extra NI years to be credited to your record – If you’re not yet claiming state pension, the payment can take up to 60 working days to process, after which you should see your NI record change. If you are claiming a state pension, HMRC will prompt the DWP to conduct a ‘benefit review’ so your payments won’t increase straightaway. However, the DWP will backdate the increase to the date you made the payment (NOT when you started claiming state pension).
ALWAYS Take Asymmetric Returns
One of my investing philosophies is always taking asymmetric returns when available.
Minimal risk for maximum benefit.
If you’re missing NI contribution years between 2006 and 2016 and you’re above the age of 40, it’s worth serious consideration.
Paying up to £824 to fill a missing year could provide an additional £302.64 /year in income.
If you read last week’s Newsletter, you’ll know about the 4% Safe Withdrawal Rate (SWR) for investing towards Financial Freedom.
That £302.64 /year could be comparable to an investment pot worth £7,566 (£302.64 x 25).
If you buy 16 years, it could be comparable to a pot worth £121,056 (£4,842.24 x 25)
Take the easy wins when they’re available.
But before you pay a penny, remember #6 above:
- Read Martin’s complete guide HERE.
- Call the ‘Future Pension Centre’ (if you’re not receiving the State Pension) or the ‘Pension Service’ (if you’re receiving the State Pension) to get personalised information on your situation.
Reflect and share this with someone.
ASK
“Do you know if you’re on track to receive a full State Pension?”
If not…
“How much will it cost to get you there?”
Write down what comes to mind.
TRY
If you’re based in the UK, it’s worth checking if you’re on track to qualify for the full State Pension.
If not, there’s a simple and low-cost way to invest in ‘missing NI years’ to receive more money in retirement.
1. Check if you’re missing NI years (since 2006)
2. Get a State Pension Forecast
3. Check if you qualify for NI Credits (Automatic & Manual)
4. Consider if it’s worth topping up your State Pension
5. BEFORE PAYING – Call the Government’s Pension Helpline
6. Share this information with people you know over 40
If you qualify for the full state pension, take comfort in knowing you’ve ticked that box. ✅
Now pay it forward and help someone else maximise their State Pension.
HIT REPLY and let me know if this Newsletter helped enhance your retirement income.
Share what you paid vs what you received to help inspire others.
I read and reply to every email, and remember, I’m rooting for you!
Remember: Little by little, a little becomes a lot.
SHARE
Reply to this email and share how it went for you. Let me know if you’d prefer to remain anonymous.
SHARE your State Pension knowledge with a friend or loved one.
SHARE this Newsletter with someone over 40.
SHARE your wins with me. (What you paid vs what you received)
Lead from the front and inspire others to follow.
Have an awesome week!
Huw


